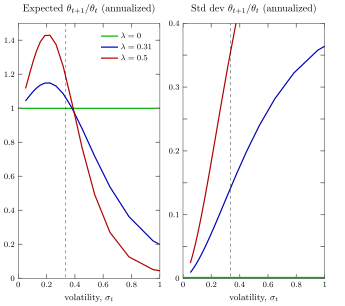
The expected aggregate bond-pricing factor \(\theta_{t+1}/\theta_t\) (left panel) and the standard deviation of \(\theta_{t+1}/\theta_t\) (right panel) as a function of the volatility state \(\sigma_t\), all expressed in annual terms. Three cases are shown, the frictionless case (\(\lambda=0\)), our benchmark (\(\lambda=0.31\)), and a high segmentation case (\(\lambda=0.5\)). The vertical dashed line is the unconditional mean \(\bar{\sigma}\).
In the paper: Figure II. Multiplicative bond-pricing factor \(\theta_{t+1}/\theta_t\).