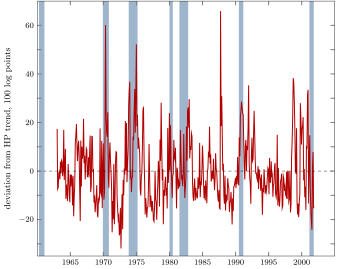
Cross-sectional standard deviation of CRSP stock returns, monthly (1963:1-2001:12), from Goyal and Santa-Clara (2003) as updated by Bali et al. (2005). Hodrick-Prescott filtered with smoothing parameter \(1600\times 3^4\), as recommended by Ravn and Uhlig (2002) for monthly data. NBER recession dates shaded.
In the paper: Figure 2. Cross-sectional standard deviation of stock returns.